 By CryptoSlate | Created at 2026-10-10 15:45:39 | Updated at 2026-10-10 17:34:39
3 hours ago
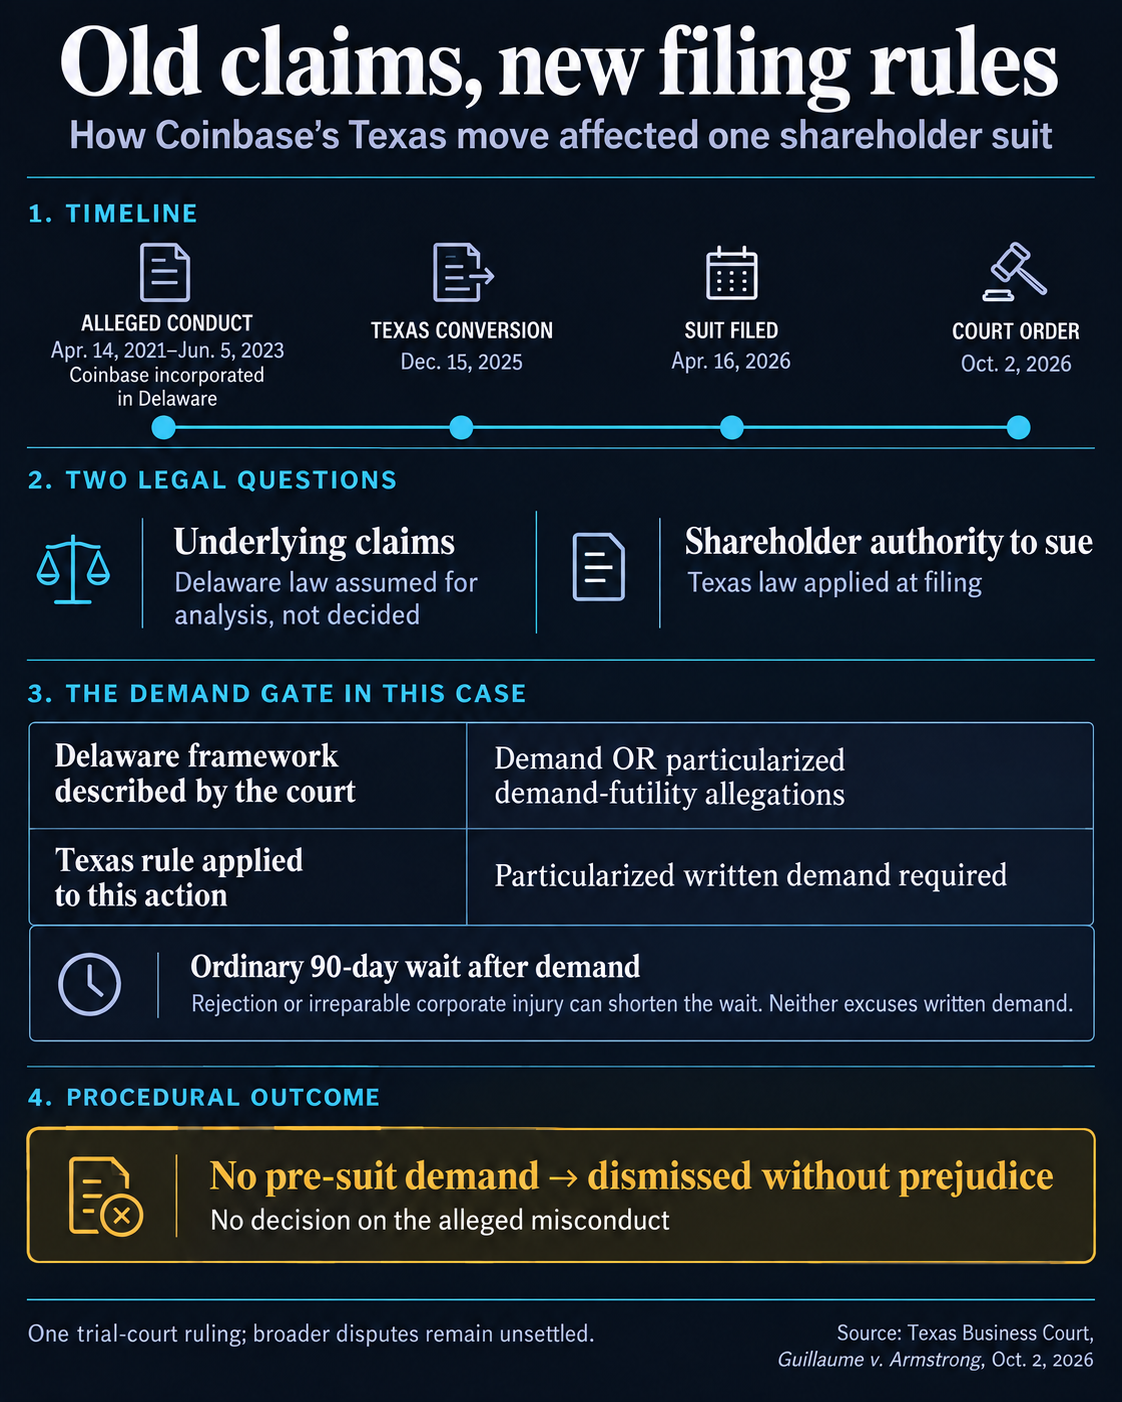
Coinbase’s move to Texas changed the rule a shareholder had to satisfy before suing its directors over alleged conduct from the company’s Delaware years. In an October 2 ruling, the Texas Business Court dismissed Gary Guillaume’s derivative action because he had not first demanded that Coinbase take action on the claims.
The dismissal was without prejudice, and the court did not decide whether the alleged misconduct occurred. Its consequential finding concerned who could pursue claims belonging to Coinbase: Texas’s demand requirement applied to the shareholder’s authority to sue, even though the court assumed without deciding that Delaware law governed the underlying claims.
On October 9, Coinbase CEO Brian Armstrong praised the precedent as encouraging more companies to incorporate in Texas and thanked Greg Abbott. That endorsement came a week after Judge Andrea K. Bouressa signed the order. The immediate lesson for public shareholders is that the law governing a company’s past conduct and the law governing their ability to challenge it can diverge after reincorporation.
Why older claims faced Texas’s demand rule
A derivative action lets a shareholder pursue a claim on the corporation’s behalf. The claim belongs to the company, and the shareholder seeks to exercise authority ordinarily held by its board. That distinction explains why the first dispute here concerned permission to bring the action rather than the directors’ alleged wrongdoing.
The parties agreed that Guillaume filed his suit on April 16, 2026, alleging misconduct between April 14, 2021, and June 5, 2023. Coinbase was incorporated in Delaware during that earlier period. Its Texas conversion became effective on December 15, 2025, several months before the suit was filed.
Under the Delaware framework described in the opinion, a derivative plaintiff can make a demand or plead that doing so would be futile. Futility requires particularized allegations about individual directors, examining whether they received a material personal benefit, face a substantial likelihood of liability, or lack independence from someone who benefited or faces such liability. At least half the relevant board must satisfy the test.
Guillaume tried that route. He did not make a pre-suit demand.
For this action involving a public company, Texas required a particularized written demand identifying the disputed conduct and requesting suitable corporate action. The October 2 opinion described an ordinary 90-day wait after demand, with derivative proceedings permitted from the 91st day. Corporate rejection of the demand or irreparable injury to the corporation can shorten the waiting period. Both exceptions leave the written-demand requirement in place.
Guillaume’s futility allegations could not substitute for the written request Texas required. The missing demand was enough to end this action before the court reached its merits.
Guillaume argued that Delaware law should apply because the claims arose before Coinbase’s Texas move. Bouressa accepted that premise about the underlying claims for purposes of the analysis, without resolving it.
She then considered a separate question: which state’s law governed the shareholder’s authority to file those claims for Coinbase?
The court’s answer turned on the company’s incorporation when the shareholder exercised that authority. A corporate claim can arise under one state’s law, while a later effort to pursue it derivatively is governed by another state’s rules. The opinion reasoned that a shareholder does not acquire a vested right, when a corporate claim arises, to bring it personally on the corporation’s behalf at some later date.
That reasoning gives reincorporation consequences beyond future board decisions. In this case, the December 2025 conversion affected the route for challenging alleged conduct dating back to 2021.
Coinbase’s conversion disclosures supplied Guillaume with another argument. He relied on language preserving eligible shareholders’ standing and ability to bring derivative claims concerning earlier conduct, subject to continued ownership.
The opinion’s treatment of that language was narrower than Guillaume’s interpretation. The court said it did not promise that Delaware law would continue to govern shareholder authority after conversion. The disclosures also expressly said Texas law would govern Coinbase’s affairs following the move.
Bouressa further found that Guillaume offered no argument or evidence showing how losing the option to plead demand futility adversely affected his ability to sue. He had not shown that making a demand was impossible, irreparably harmful or prejudicial, or that the futility option gave him a particular advantage.
The court also found no evidence that Coinbase had successfully contracted around the Texas requirement.
Concentrated votes, a different accountability route
The governance backdrop makes that distinction matter. Coinbase’s November 2025 information statement said the Armstrong- and Fred Ehrsam-associated consenting group held approximately 78.40% of voting power at the October 31, 2025 record date. The group approved the conversion by written consent on November 4.
Coinbase said a committee of Christa Davies and Paul Clement, whom the board found independent and disinterested, evaluated Delaware, Nevada and Texas before recommending Texas. The board unanimously approved the move.
The company cited greater litigation predictability, potential savings on defense costs, indemnification and insurance, and Texas’s crypto-friendly environment.
The consent figure describes approval in 2025. In its April 24, 2026 proxy, Coinbase reported March 31 voting-power figures of 49.6% for Armstrong, 18.9% for separately listed Armstrong-associated entities and trusts with an independent trustee, and 10.6% for Ehrsam. The figures use SEC beneficial-ownership rules, including qualifying options. Class B shares carry 20 votes each, compared with one for Class A.
Coinbase’s February 2026 annual filing described Armstrong and the independent trustee collectively as able to exercise majority voting rights. Its July 30 quarterly filing reported no material changes to the annual risk factors, without supplying a new individual voting-power percentage.