 By The Diplomat | Created at 2026-10-13 23:12:07 | Updated at 2026-10-14 00:07:03
8 hours ago
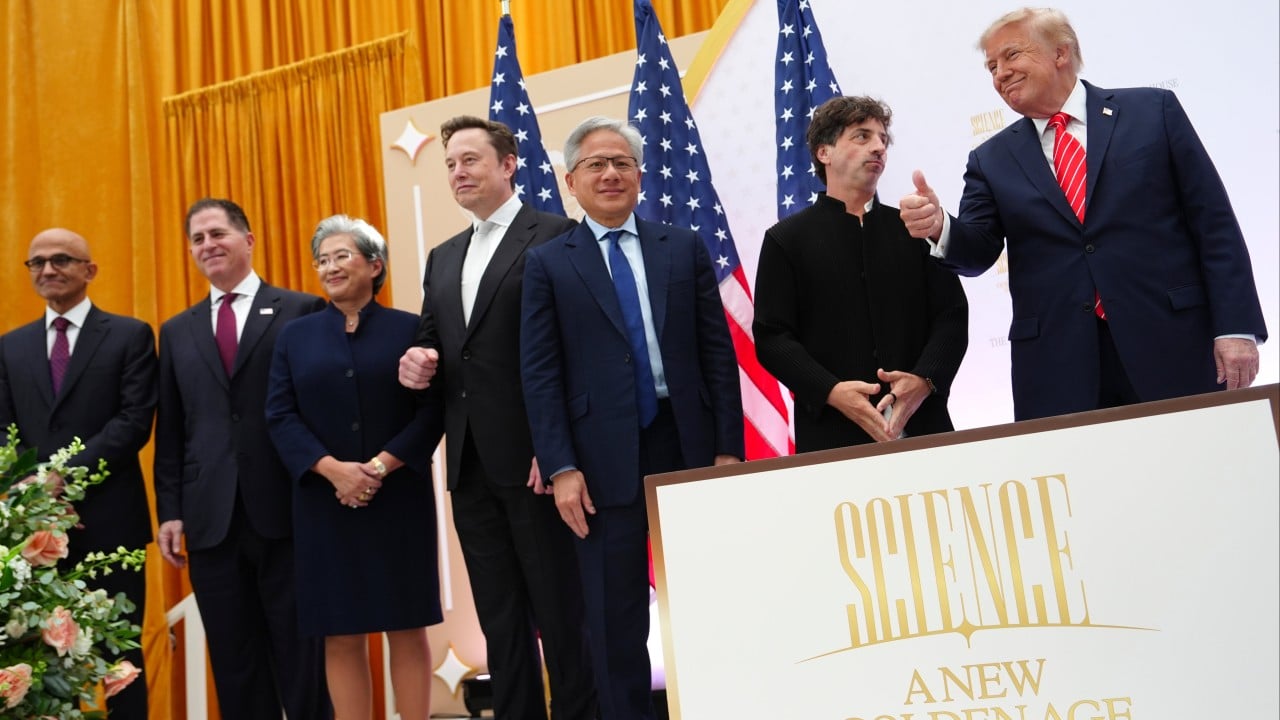
On September 28, Trump invited Iowa Representative Ashley Hinson, the Republican running for an open Senate seat, to the Oval Office to announce a new $15 billion steel plant in her home state, which is being built by the local subsidiary of an Indian conglomerate. Two days later, with Alaska Senator Dan Sullivan standing beside him, Trump announced roughly $54 billion in prospective South Korean investment in the Alaska LNG pipeline.
Notably, both announcements came a little over a month before the midterm elections. The Associated Press noted that it was “the second time in three days” Trump had paired a major investment announcement with a Republican Senate candidate in a race that had become unexpectedly competitive.
Seoul described the Alaska announcement quite differently. South Korean Industry Minister Kim Jung-kwan said it went “far beyond what was agreed,” while his ministry said it had not decided whether to invest or how much. The U.S. Commerce Department’s fact sheet was more conditional: the two sides had agreed to begin work on Alaska LNG, subject to commercial reasonableness and domestic legal requirements.
Similarly, Washington also presented a roughly $22 billion Texas project and a nuclear framework valued at up to $120 billion. Again, Seoul has indicated a more cautious approach to those investments, with individual reactor projects still under review. In other words, the headline figures may not all materialize.
The election wasn’t the driving force behind these projects or negotiations, which have been in the works for nearly a year. But the announcements have clear electoral value. On September 30, Trump said he had done “a very bad job of explaining how good the country is doing.” The Iowa and Alaska events show how investment announcements involving U.S. partners are being caught up in Trump’s pre-election economic messaging.
The approaching elections – and polling suggesting that a number of Republican seats in Congress are at risk – increases the political value of presenting long-term allied investment plans as immediate economic wins. Both South Korea and Japan had agreed to invest hundreds of billions of dollars in the United States as part of overall economic deals reached in 2025 with the Trump administration. The upcoming election may be impacting the announcement of specific projects under those investment pledges – although it’s hard to establish the connection definitively. It’s also possible that Japan and South Korea could use Trump’s sense of urgency over specific projects to leverage better terms.
The structure of the deals is responsible for some of the confusion. The Korean and Japanese “agreements” are actually administrative arrangements that create no legally binding obligations. Under the standard timetable, actual funding is not required until at least 45 business days after an ally is notified that the president has selected a project. South Korea’s domestic law adds another layer: investments are, in principle, reviewed for commercial reasonableness and other considerations, examined by a government committee, and reported to relevant National Assembly committees before Seoul consults Washington. In other words, there’s a month-plus gap between any political announcement and the point at which money actually changes hands.
Before the Alaska announcement, Washington was pressing for faster progress, while Seoul emphasized commercial rationality. The planned announcement had already been postponed while such differences remained unresolved. The election may have given Seoul temporary bargaining room, even as Washington remained the much stronger party. When one side values speed more than the other, delay itself can become bargaining leverage.
Japan offers an important comparison because its investments have been moving more quickly. On February 17, Trump announced the first $36 billion of Japan’s $550 billion investment pledge. Tokyo’s first financing agreement came about 10 weeks later, on May 1, and provided roughly $2.2 billion for that initial batch of projects. By September, Japan had announced two project rounds totaling about $109 billion.
The gap between announcement and financing is relatively baked in. In that sense, the midterms may be amplifying an existing practice rather than creating a new one.
When evaluating major investment announcements, it’s important to look beyond the topline figure to other data points: what the partner government has actually approved, when funding will actually arrive, and which political or diplomatic events might be impacting the timing.
A new Japanese investment package before November 3 would strengthen the case that the U.S. election calendar is influencing announcement timing. If the next investment announcement isn’t made until the November 18-19 APEC leaders’ meeting in Shenzhen, however, it would mean the diplomatic calendar is more influential. These explanations are not mutually exclusive: an announcement can advance negotiations abroad while producing political value at home.
The same logic applies to allied behavior. Resistance, delay, or demands for safeguards by Japan and South Korea may suggest the allies have greater bargaining room, but would not by themselves prove that electoral pressure caused a concession from the Trump administration. Remember, these investment pledges are around a year old; the process has been moving slowly from the start.
The midterms are not overhauling U.S. economic policy toward Seoul and Tokyo, but they could make the Trump administration keen to announce progress early – even before funding actually comes through.