 By The Rio Times | Created at 2026-10-03 07:36:51 | Updated at 2026-10-03 08:23:19
1 hour ago
Key Facts
- The rand firmed a little: the US dollar eased 0.33% to about R16.64 late on Friday, after Thursday’s slide of about 1.6%, but the rand still lost about 2.2% over the week
- Johannesburg shares rose: the Satrix 40 ETF, which tracks the FTSE/JSE Top 40 index, gained 0.81% to R102.77 (US$6.18), yet it fell 2.2% on the week
- Capitec rebounded: the bank rose 4.4% to R4,372.69 (US$262.74) on turnover of R1.87 billion (US$113 million), the most of any JSE stock
- Diversified miners led: Glencore rose 3.8%, Anglo American 3.3% and BHP 2.1%, while gold miners were mixed
- US jobs data missed: American employers added 29,000 jobs in September against a forecast of about 90,000, and unemployment rose to 4.2%
- Fuel prices are next: the October petrol and diesel adjustment is announced on Monday 5 October, with 95 petrol projected near R30.13 (US$1.81) a litre, a record
Today’s Focus
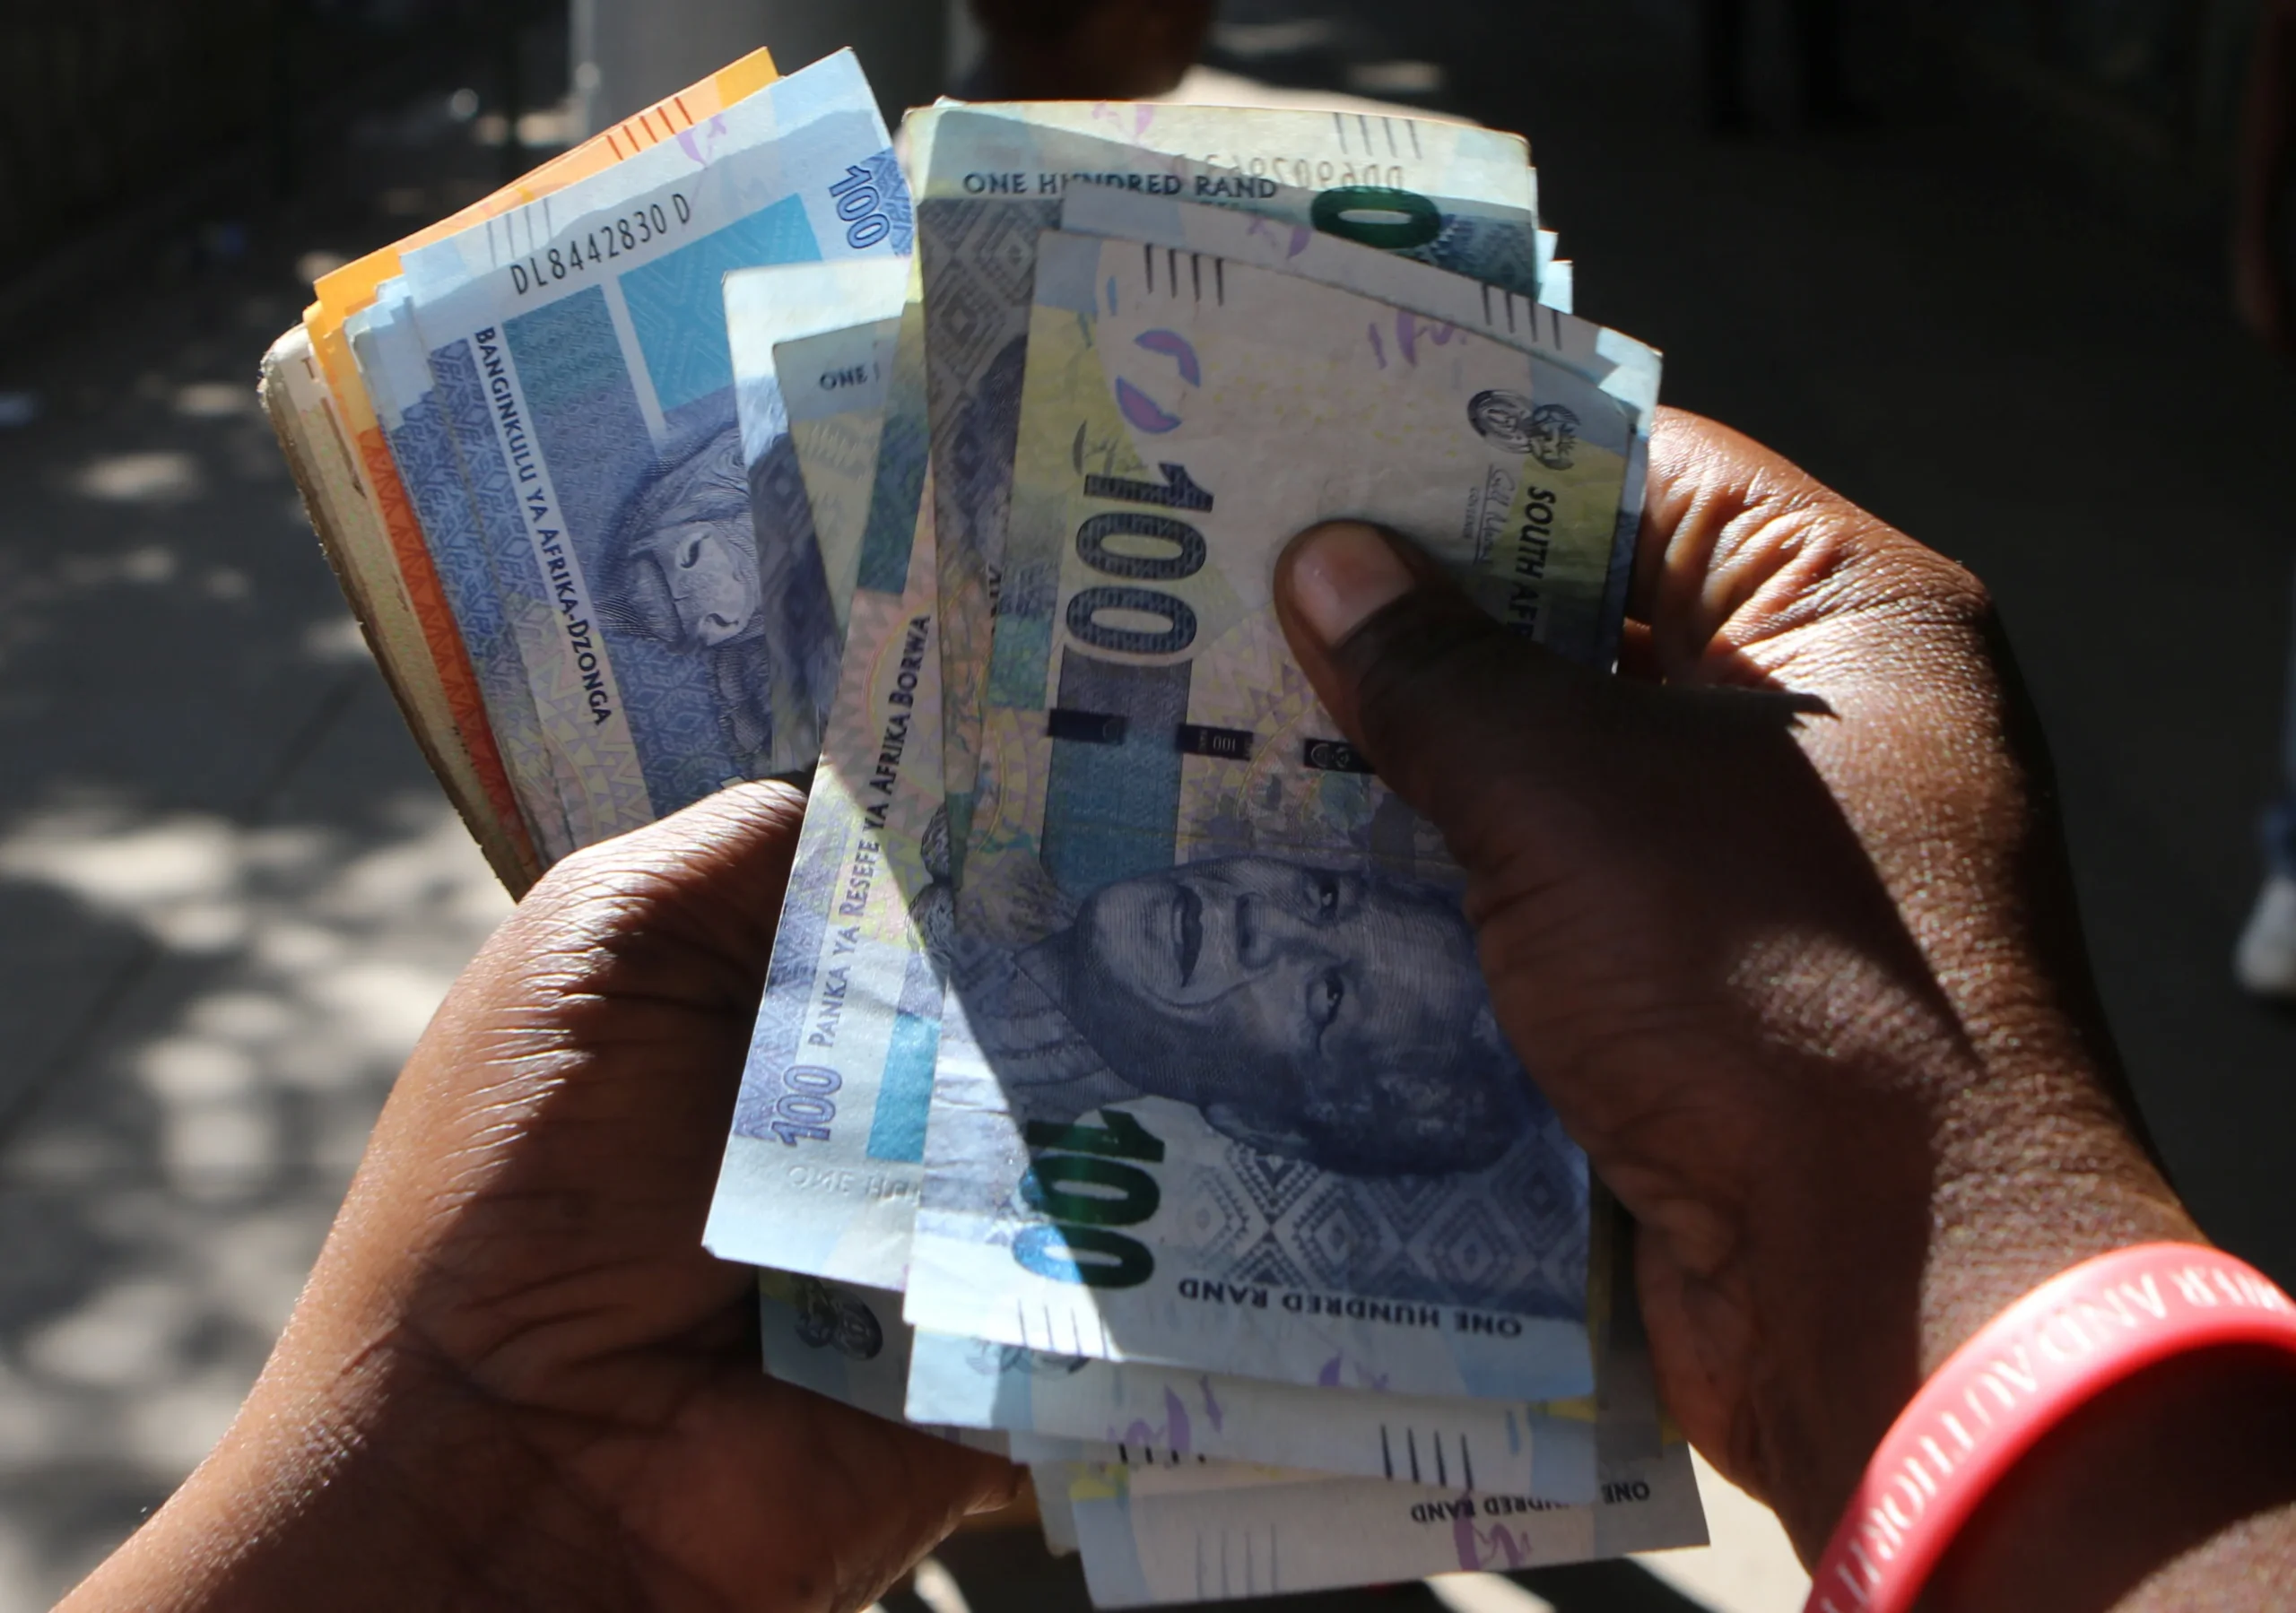
South Africa’s rand steadied on Friday, 2 October 2026, and Johannesburg shares rose. The US dollar slipped 0.33% to about R16.64, but the rand still ended its fourth straight weekly loss.
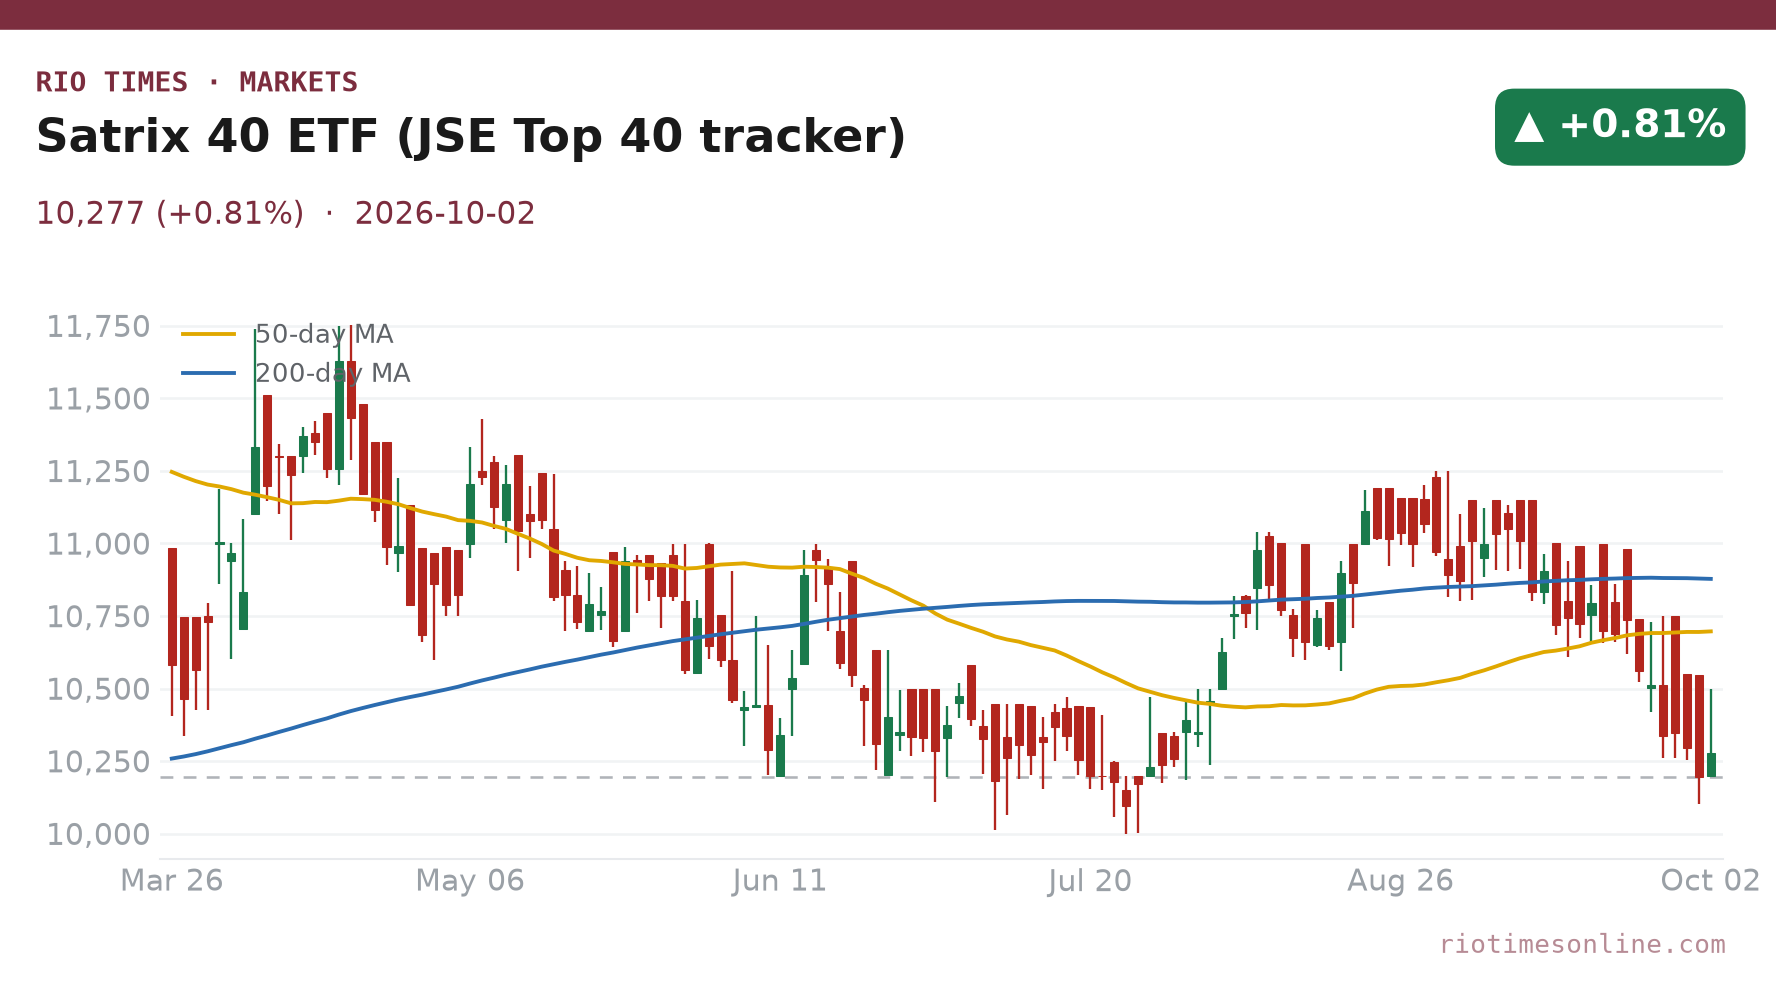
The Satrix 40 ETF, an exchange-traded fund that tracks the FTSE/JSE Top 40 index of the largest listed companies, gained 0.81% to R102.77 (US$6.18). Capitec led the way with a 4.4% rebound. Glencore, Anglo American and BHP also rose.
The lift came after weak US jobs data pulled the dollar lower. American payrolls rose by only 29,000 in September, well below the roughly 90,000 economists expected.
What matters today. A steadier rand is welcome news before the fuel price announcement on Monday. A weaker rand makes petrol and imports dearer for South Africans, and it cuts the cost of a holiday or an investment for anyone earning dollars. The question for next week is whether Friday was a pause or the start of a recovery.
One-stop reference
Company Intelligence
Every listed company in Latin America — financials, ownership and structure for 1,450+ companies across 26 exchanges, in one place.
01 The session in one read
The Johannesburg Stock Exchange (JSE), Africa’s largest stock market, ended Friday higher. The Satrix 40 ETF closed at R102.77 (US$6.18), up 0.81% from Thursday’s R101.94. We use the ETF as a tracker because an official closing level for the FTSE/JSE Top 40 index was not available to us at the time of writing. Early in the session, CNBC Africa reported that the Top 40 index was up 0.9%.
Breadth was positive. Among 383 JSE instruments with prices on both days, 236 rose, 125 fell and 22 were unchanged. The ETF opened at R102.00, reached R104.99 and closed well below that high. About 767,700 units changed hands, roughly 53% more than on Thursday.
The most active share was Capitec, a fast-growing retail lender. It rose 4.4% on R1.87 billion (US$113 million) of trade. The other big banks also gained, with Standard Bank up 1.1%, Absa 0.8%, Nedbank 0.7% and FirstRand 0.2%.
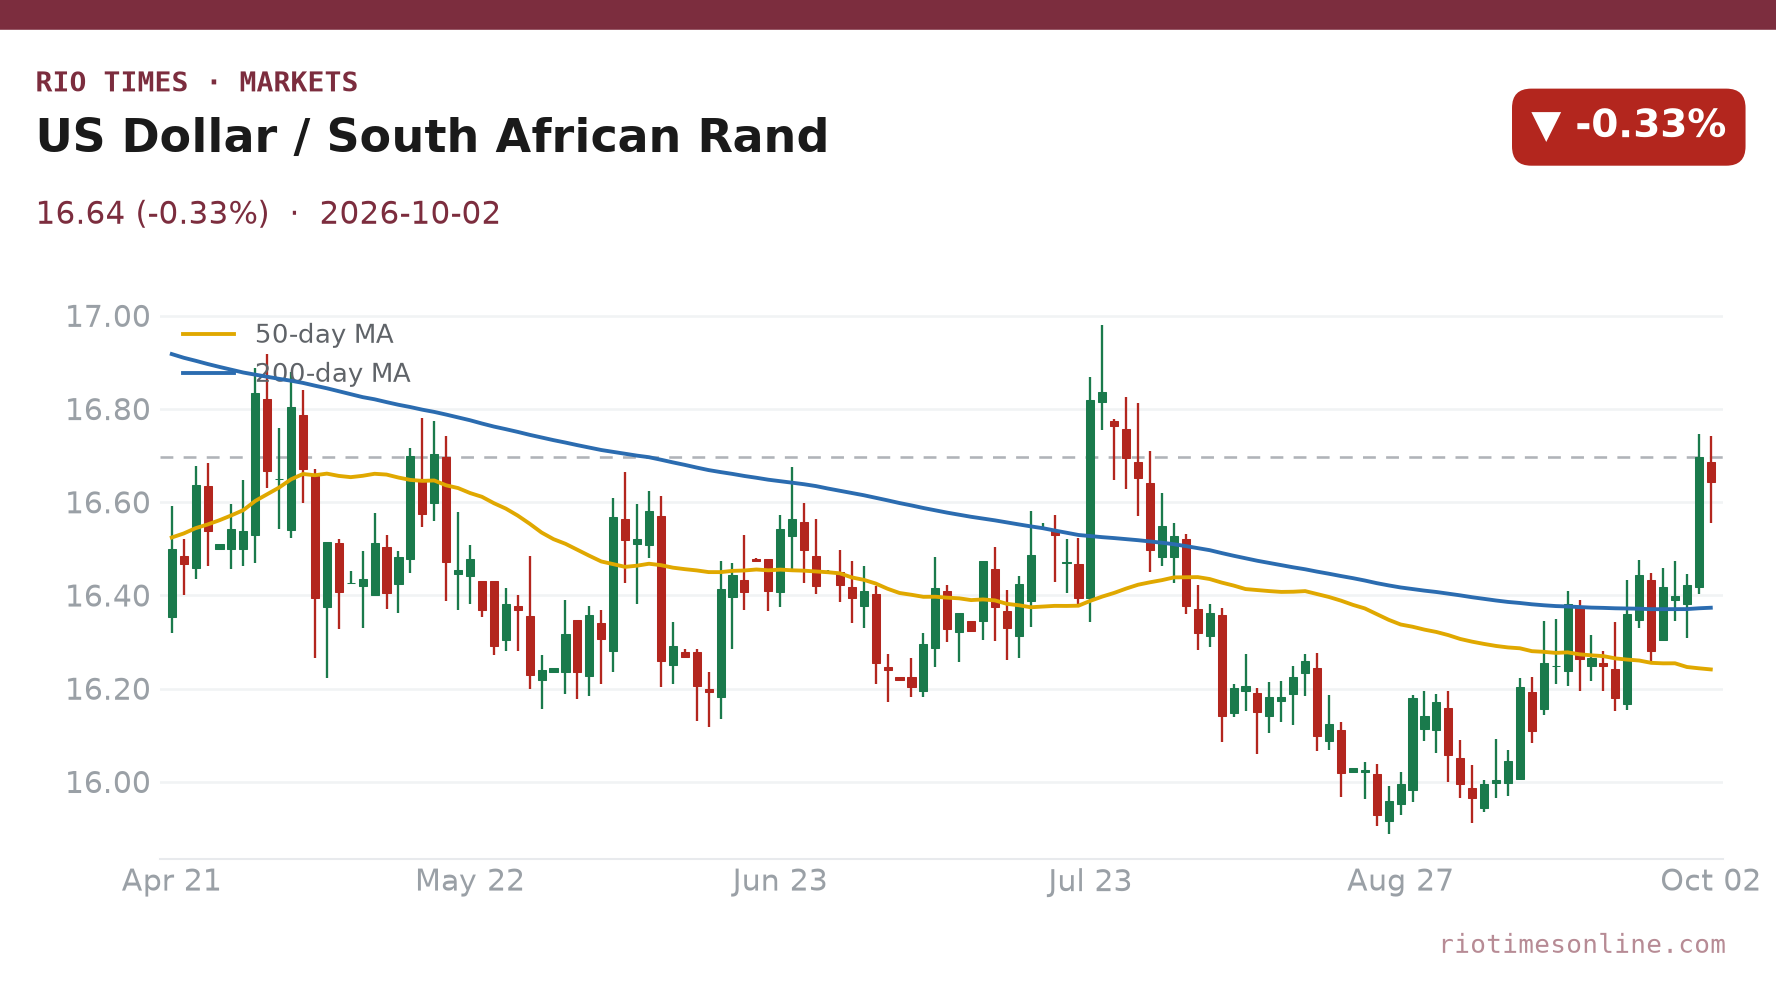
The rand moved in a narrow range. The US dollar traded between R16.55 and R16.74 and closed at R16.64, down 0.33% from Thursday’s R16.70. The rand was weaker against the euro, down 1.0%, and the British pound, down 1.2%.
Assessment: A dollar-led pause, not a turnaround MEDIUM
The pattern fits a softer dollar after the US jobs report. The rand firmed against the dollar but lost ground against the euro and the pound, which points to the dollar rather than the rand as the main mover. Shares recovered part of Thursday’s losses, yet the tracker still ended the week 2.2% lower. What we cannot confirm is why Capitec rebounded so sharply, because we found no company news on the day beyond its half-year results on Wednesday. Without an official index close, the size of the Top 40 gain is also an estimate.
02 The day’s numbers
| Satrix 40 ETF (Top 40 tracker) | R102.77 | +0.81% | Down 2.2% on the week; 14.5% below its 12-month high |
| USD/ZAR | 16.64 | −0.33% | Rand firms slightly; still down 2.2% on the week |
| EUR/ZAR | 18.78 | +0.99% | Rand loses ground against the euro |
| GBP/ZAR | 22.04 | +1.19% | Rand also weaker against the pound |
| US nonfarm payrolls (September) | +29,000 | Forecast about 90,000 | Previous month revised to 133,000; unemployment 4.2% |
| JSE breadth (383 instruments) | 236 up | 125 down | 22 unchanged |
Over the past 12 months the Satrix 40 ETF has closed between R100.34 (4 November 2025) and R120.21 (27 February 2026). Friday’s close leaves it 14.5% below that peak and only 2.4% above the low. In September the tracker fell 6.1%.
The dollar has traded between R15.74 (29 January 2026) and R17.53 (4 November 2025) over the same period. At R16.64 it sits roughly in the middle of that range. It has gained 3.1% since the end of August, when it closed at R16.14.
Rio Times · Live Market Intelligence
Global Markets — Live Board
World
Oct 3, 2026 · 03:55
S&P 500 · benchmark
7,751 +0.29%
Market breadth · 15 names
60% advancing
9 ▲ advancing6 declining ▼
Currencies, rates & key inputs
Full instrument board
| SPX | 7,751 | +0.29% | — | — | — | — | — |
| NDX | 29,799 | +0.93% | — | — | — | — | — |
| DJI | 53,810 | +0.03% | — | — | — | — | — |
| RUT | 3,041 | +0.46% | — | — | — | — | — |
| US10Y | 4.6760 | -0.17% | — | — | — | — | — |
| VIX | 14.60 | -4.45% | — | — | — | — | — |
| DAX | 26,331 | -0.23% | — | — | — | — | — |
| FTSE | 10,833 | -0.10% | — | — | — | — | — |
| CAC | 8,675 | -0.46% | — | — | — | — | — |
| STOXX | 659.48 | -0.16% | — | — | — | — | — |
| NIKKEI | 67,524 | +0.83% | — | — | — | — | — |
| HSI | 25,440 | -0.83% | — | — | — | — | — |
| KOSPI | 6,579 | +3.68% | — | — | — | — | — |
| CSI300 | 4,691 | +0.58% | — | — | — | — | — |
| NIFTY | 24,436 | -0.15% | — | — | — | — | — |
| TSX | 36,619 | +0.39% | — | — | — | — | — |
| GOLD | 4,461 | +1.78% | +33.20% | 4,383 | 4,503 | 4,421 | 139,824 |
| SILVER | 65.59 | +1.26% | +73.05% | 64.77 | 66.98 | 64.81 | 46,406 |
Largest moves today
VIX 14.60 -4.45%
KOSPI 6,579 +3.68%
GOLD 4,461 +1.78%
SILVER 65.59 +1.26%
NDX 29,799 +0.93%
NIKKEI 67,524 +0.83%
HSI 25,440 -0.83%
CSI300 4,691 +0.58%
The session read
The S&P 500 rose 0.29%, with breadth positive — 9 of 15 names higher. KOSPI led, while HSI lagged.
03 Why it moved: a softer dollar and a Capitec rebound
The main outside driver was the US jobs report, published at 13:30 Lisbon time (12:30 UTC). Payrolls rose by 29,000 against a forecast of about 90,000, and unemployment edged up to 4.2% from 4.1%. Weak jobs data tends to lower US interest-rate expectations, and that usually weighs on the dollar. Emerging-market currencies such as the rand often gain when it does.
The rand had been under pressure all week. CNBC Africa, citing Reuters, reported that higher US bond yields were drawing money away from emerging markets, and that the rand was heading for its fourth weekly loss. The South African Reserve Bank (SARB) added to the stress on borrowers when it raised its policy rate by 25 basis points to 7.25% on Wednesday, 23 September.
Banks bounced back on Friday. Capitec had fallen 3.6% on Thursday, a day after it reported half-year headline earnings up 19% to R9.5 billion (US$571 million). Its rebound of 4.4% on Friday is large. We could not find a company announcement that explains it, so we treat it as a recovery in sentiment.
Diversified miners also helped. Glencore, Anglo American and BHP rose between 2.1% and 3.8%. Gold shares were mixed: AngloGold Ashanti gained 0.6%, while Gold Fields fell 1.2% and Harmony 0.9%. Spot gold jumped 0.9% to US$4,216 an ounce right after the jobs data and then gave back most of that gain, according to BullionVault.
04 Friday’s news and data, one by one
Four items shaped the mood in Johannesburg. One came from Friday itself, the others from earlier in the week or as a projection.
US jobs report (Bureau of Labor Statistics). Nonfarm payrolls rose 29,000 in September. Economists had forecast about 90,000, and August was revised down to 133,000. The unemployment rate rose to 4.2%. The data came out at 12:30 UTC and was the main global event of the day. The RT calendar listed no South African data releases on Friday.
Capitec results. Capitec reported on Wednesday 30 September that headline earnings for the six months to 31 August rose 19% to R9.5 billion (US$571 million). It declared an interim dividend of 3,110 cents per share (R31.10, or US$1.87) and said active clients rose 7% to 26.6 million. The shares fell on Thursday and rebounded on Friday.
Producer prices and trade (Stats SA, SARS). Producer inflation slowed to 5.0% a year in August from 5.7% in July. The trade surplus widened to R20.5 billion (US$1.23 billion), as imports fell 7.8% to R161.3 billion (US$9.69 billion) and exports fell 5.8% to R181.8 billion (US$10.92 billion). Both releases were better than economists had expected.
Fuel prices. The Central Energy Fund projects that inland 95 petrol will rise by about R3.21 (US$0.19) to R30.13 (US$1.81) a litre. Diesel (50ppm) would rise by about R3.15 (US$0.19) to R31.86 (US$1.91). The official figures come on Monday 5 October and apply from midnight on Wednesday 7 October. Our full report is here.
05 The day’s movers
| Capitec (CPI) | R4,372.69 (US$262.74) | +4.4% | Most-traded stock: R1.87bn (US$113m) |
| Glencore (GLN) | R124.40 (US$7.47) | +3.8% | R209m (US$13m) traded |
| Anglo American (AGL) | R906.64 (US$54.48) | +3.3% | R286m (US$17m) traded |
| BHP Group (BHG) | R708.40 (US$42.57) | +2.1% | R560m (US$34m) traded |
| MTN Group (MTN) | R183.77 (US$11.04) | +1.8% | R895m (US$54m) traded |
| Gold Fields (GFI) | R592.02 (US$35.57) | −1.2% | R1.62bn (US$97m) traded; second most active |
| Shoprite (SHP) | R311.59 (US$18.72) | −2.2% | R488m (US$29m) traded; weakest of the liquid shares |
The table shows a market led by Capitec and the big miners. Capitec alone traded R1.87 billion (US$113 million), more than any other stock. Gold Fields was next with R1.62 billion (US$97 million), although it closed lower. AngloGold Ashanti traded R1.09 billion (US$65 million) and rose 0.6%.
Banks mostly gained. FirstRand traded R833 million (US$50 million) and rose 0.2%, and Standard Bank gained 1.1%. For readers who follow the companies, our JSE Limited profile explains how the exchange itself is run.
Outside these groups, telecoms group MTN gained 1.8% and Vodacom 2.9%. Shoprite, the grocery retailer, was the weak spot among large stocks, down 2.2%. Our table lists only shares with at least R50 million (US$3 million) of turnover.
06 The regional scoreboard
| Satrix 40 ETF (Top 40 tracker) | South Africa | +0.81% |
| NGX All-Share Index | Nigeria | −0.16% |
Nigeria’s All-Share Index closed at 250,808.27 points. The change is measured against Wednesday 30 September, because the Nigerian Exchange was shut on Thursday for Independence Day. Egypt’s EGX30 does not trade on Fridays.
Closing data for Nairobi and Casablanca are left out here rather than estimated. On the evidence available, Friday’s gain was a South African story tied to the dollar and to Capitec, not a pan-African rally.
07 The technical picture
The Satrix 40 ETF closed at R102.77, only 2.4% above its 12-month closing low of R100.34. A fall below that mark would put the tracker at its weakest level in a year. Friday’s session low of R101.94 equalled Thursday’s close and is the first line to watch. In our chart the tracker still trades below both its 50-day and its 200-day moving average.
For the rand, the next marker is the late-July closing high for the dollar. The dollar closed at R16.84 on 24 July 2026. A move through that level would leave the rand at its weakest since early April.
On the upside for the rand, a return to R16.42, the dollar’s close on Wednesday 30 September, would erase this week’s slide. That would need a calmer dollar and steady local data.
08 What to watch
- Fuel price announcement, Monday 5 October: The Central Energy Fund projects record petrol and diesel prices from Wednesday 7 October; the final figures decide how much extra pressure lands on inflation
- S&P Global South Africa PMI, Monday 5 October: The private-sector survey is due at 07:15 UTC (08:15 Lisbon, 09:15 Johannesburg), with a forecast of 50.7 against 50.5 before; a reading above 50 signals growth
- Rand at R16.84: The dollar’s late-July closing high is the next test; a break would add pressure on fuel prices and inflation
- Capitec follow-through: After a 3.6% fall and a 4.4% rebound in two days, a third session of large moves would show how nervous investors are about the bank
- SARB meeting, 19 November: The central bank has raised rates twice this year and expects inflation to climb above 5% late in 2026
Background: Johannesburg Stock Exchange (JSE): How It Works, Who Runs It and What Issuers Must Disclose. More from the region: South Africa news, our report on Thursday’s rand slide and Gold Fields after its rebuffed Australian bid.
Frequently Asked Questions
What is the Satrix 40 ETF?
It is an exchange-traded fund listed on the Johannesburg Stock Exchange that tracks the FTSE/JSE Top 40 index, which covers the 40 largest companies on the exchange.
How did the rand and JSE shares do on 2 October 2026?
The Satrix 40 ETF rose 0.81% to R102.77 (US$6.18), and the dollar eased 0.33% to about R16.64. The rand still lost about 2.2% over the week.
Why did Capitec shares rise on Friday?
Capitec rose 4.4% to R4,372.69 (US$262.74) after falling 3.6% on Thursday. It reported 19% higher half-year earnings on 30 September. No company news explaining Friday’s rebound was found.
When are South Africa’s October fuel prices announced?
The official petrol and diesel prices are announced on Monday 5 October 2026 and take effect from midnight on Wednesday 7 October. The Central Energy Fund projects record prices.
Source: RT live market data, close of Friday 2 October 2026 (Satrix 40 ETF used as Top 40 tracker; rand rates late on Friday; RT); exchange figures from the JSE; early-session index move from CNBC Africa; US jobs data from the US Bureau of Labor Statistics; Capitec results from Capitec and Business Day; producer prices from Stats SA; trade data from the South African Revenue Service; policy rate from the South African Reserve Bank; fuel projections from the Central Energy Fund.
This article was produced by The Rio Times’ automated newsroom system. How we use AI · Report an error · Editorial responsibility: Matthias Camenzind, Editor-in-Chief
LatAm Markets: Live Signals → — real-time movers, turnover leaders and FX across Latin America.