 By The Rio Times | Created at 2026-09-10 11:06:37 | Updated at 2026-10-04 11:55:46
3 weeks ago
CHILE · CAPITAL MARKETS
Key Facts
- —The bill MK4, sent to Congress with maximum urgency on 9 September.
- —The down payment The state contributes three points of a ten percent deposit for first-home buyers who have saved seven points over 30 months.
- —The fund A new Fonavi housing fund run by BancoEstado to buy and finance around 150,000 mortgages on 30-year terms.
- —The third pillar A new stock exchange for startups and junior mining companies.
- —The reception Guillermo Tagle of Icare: it could be a really very significant leap into the future.
- —Also backing it Banco de Chile chief executive Eduardo Ebensperger called it a very positive impulse.
Chile’s fourth capital markets reform pairs a housing subsidy with a stock exchange for junior miners. The banking sector likes it, which is itself worth noticing.
One-stop reference
Company Intelligence
Every listed company in Latin America — financials, ownership and structure for 1,450+ companies across 26 exchanges, in one place.
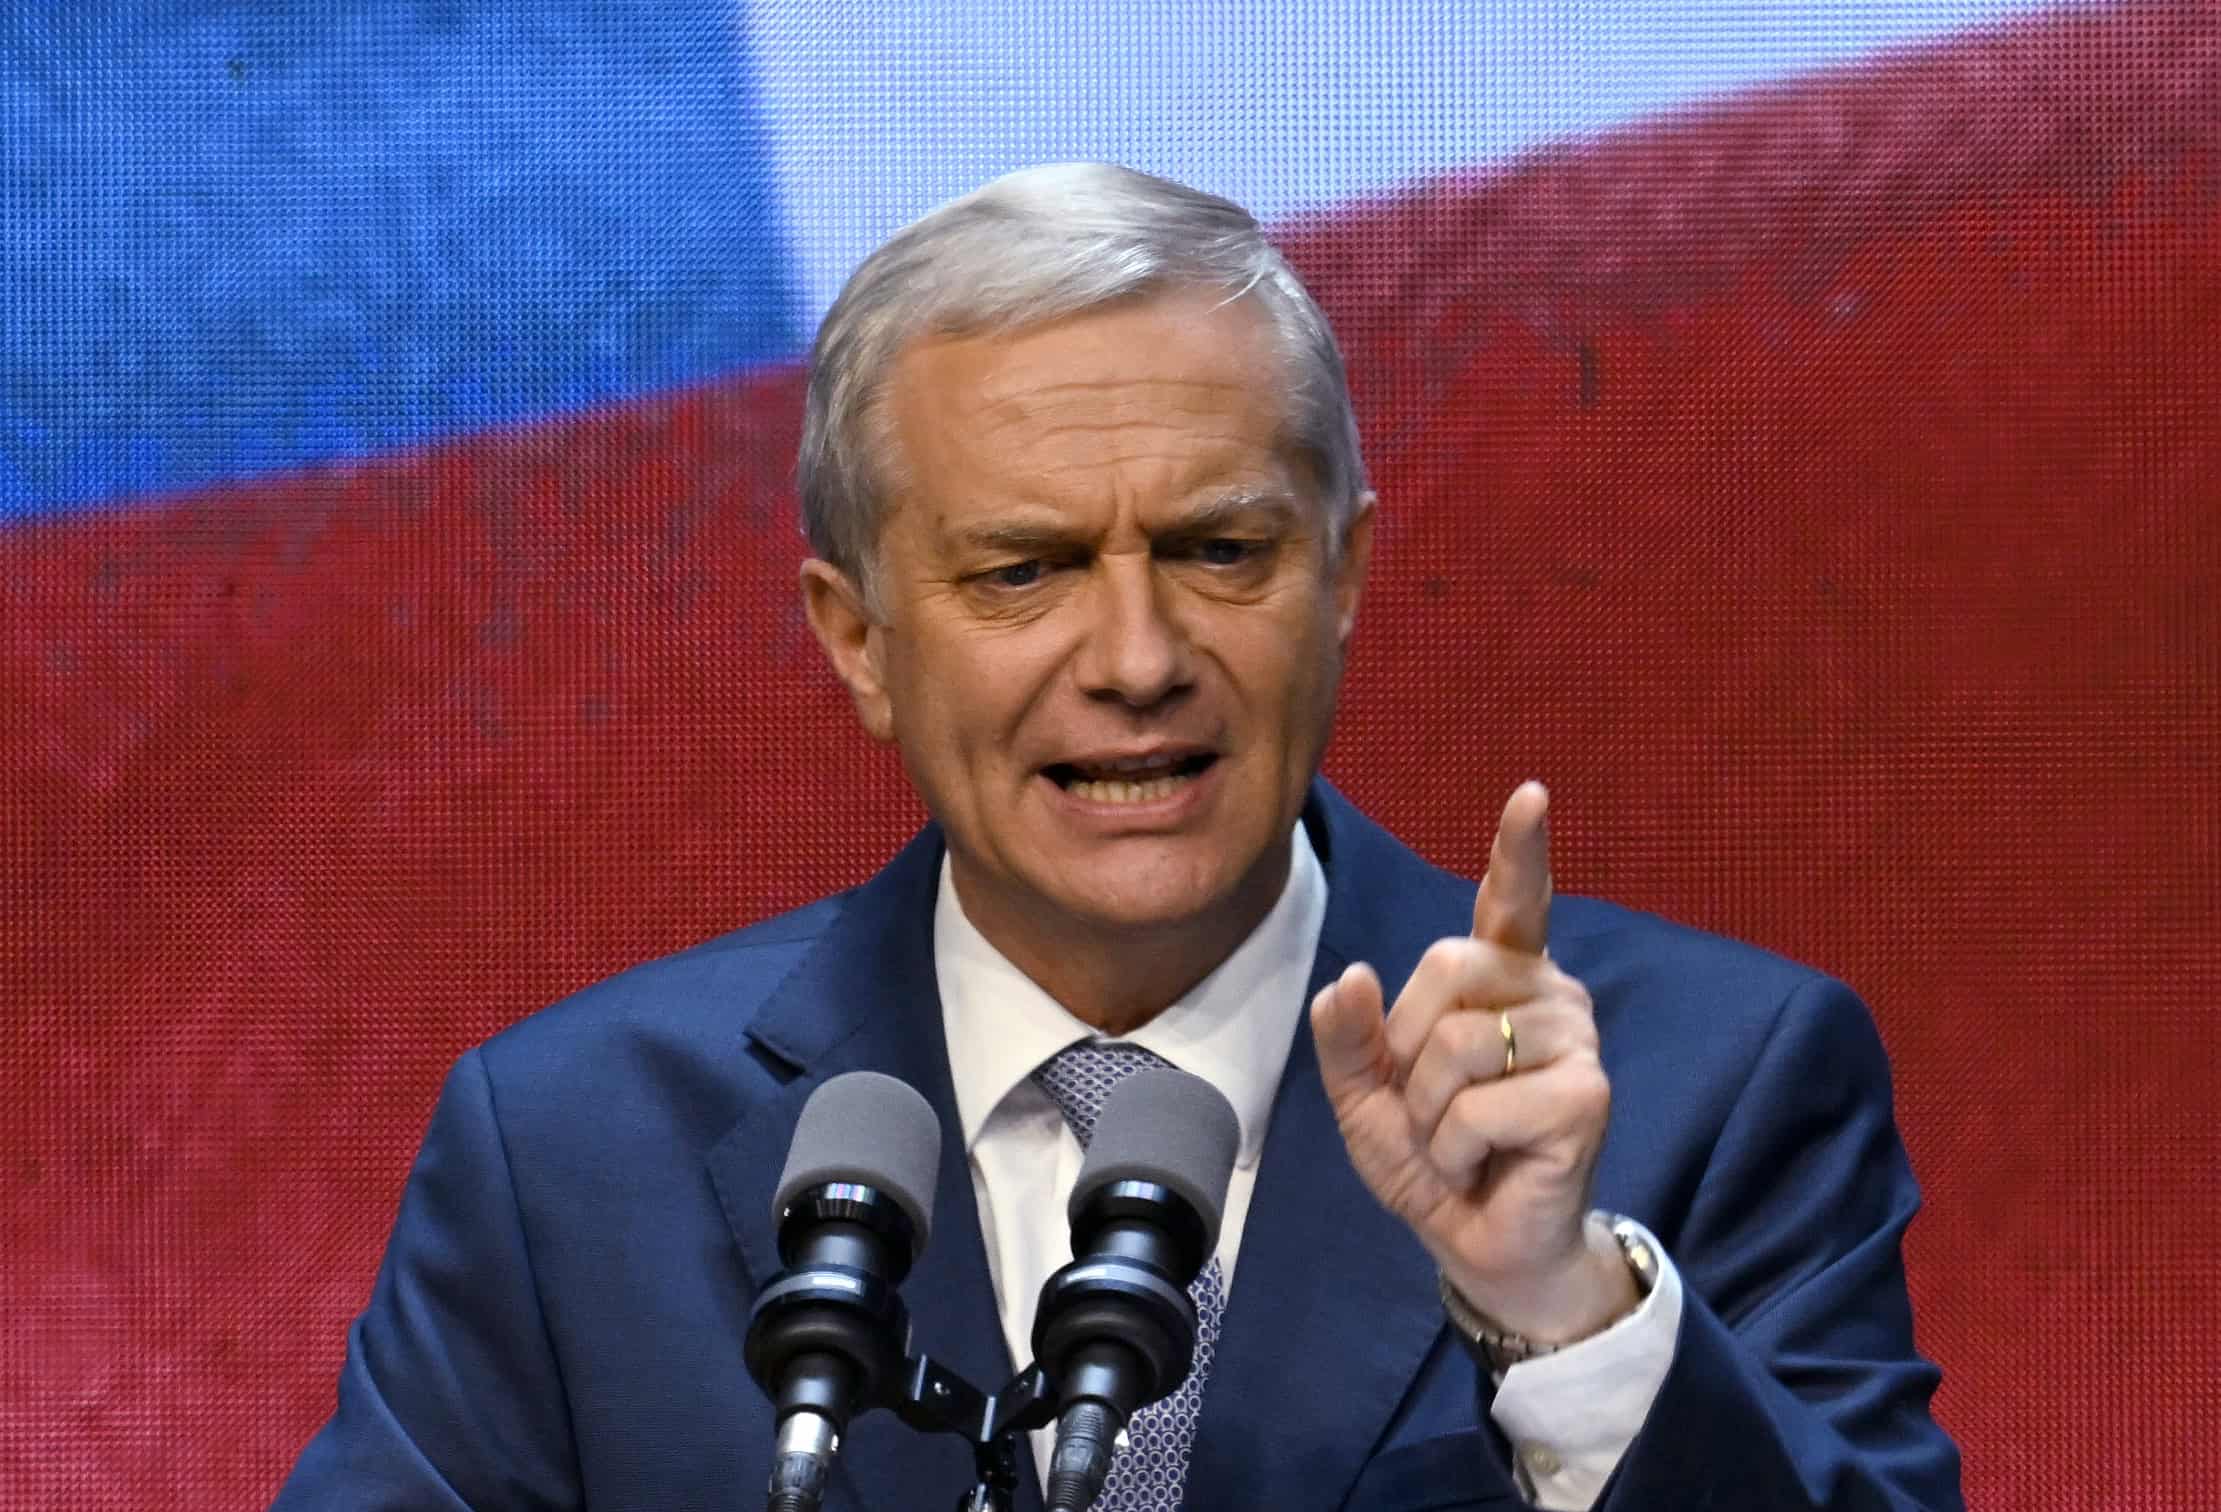
President José Antonio Kast sent Chile’s fourth capital markets reform to Congress with maximum urgency on Wednesday, pairing housing measures with a new exchange for early-stage companies.
What Is in It
The first element is a down-payment mechanism. A first-home buyer who saves seven percentage points of a ten percent deposit over 30 months receives the remaining three points from the state.
The second is a new housing fund, Fonavi, to be run by BancoEstado, which would buy and finance around 150,000 mortgages on 30-year terms. In practice that is a portfolio repurchase facility, giving lenders a route to move mortgage risk off their balance sheets.
The third is a new stock exchange aimed at startups and junior mining companies, addressing a persistent gap in Chilean equity finance where neither category has a realistic listing venue.
Kast framed the package around ownership: we need a Chile of owners rather than a Chile of tenants.
The Industry Reaction
Guillermo Tagle, president of Icare and formerly chairman of LarrainVial, said the reform could be a really very significant leap into the future.
Eduardo Ebensperger, chief executive of Banco de Chile, described it as a very positive impulse.
Enthusiasm from the banking sector for a reform that hands BancoEstado a 150,000-mortgage purchase mandate is not surprising. A repurchase facility of that size transfers duration and credit risk from private lenders to a state bank, and that is a good outcome for private lenders.
That is not an argument against the measure. It is a reason to read the enthusiasm as interested rather than as neutral assessment.
Where the Risk Sits
The down-payment contribution is a straightforward transfer. It costs what it costs and it will help people buy houses.
The Fonavi fund is the piece that deserves scrutiny. Concentrating 150,000 mortgages in a state bank creates a single institution whose balance sheet is exposed to Chilean residential credit at scale, and the quality of that exposure depends entirely on the terms at which the portfolios are bought.
Chile has a stronger record than most of its neighbours at building institutions of this kind and running them conservatively. The design detail, when the bill text is examined, is where that record will be tested.
Why Chile Needs a Housing Fix
Chilean home ownership has been falling for a decade, particularly among people under forty in Santiago and Valparaíso. The proximate cause is the deposit rather than the mortgage rate.
Chilean banks generally require a twenty percent down payment, and Chilean house prices relative to income rose substantially through the 2010s. A household that can service a mortgage often cannot assemble the deposit.
Mortgage terms tightened further after the pension withdrawals of 2020 and 2021 pushed long-term rates up, and thirty-year fixed lending became scarcer and more expensive.
The down-payment contribution attacks the first problem directly. The Fonavi fund attacks the second, by giving lenders a route to move long-duration mortgages off their books and therefore a reason to write more of them.
The Junior Mining Piece
The third element has had less attention and is arguably the more interesting one. Chile is the world’s largest copper producer and has no functioning listing venue for early-stage mining companies.
Junior miners, the small exploration companies that find deposits the majors eventually develop, list in Toronto, London or Sydney. Chilean geology gets financed by Canadian and Australian capital, and the returns accrue there.
Creating a domestic venue for that financing is a long-term structural idea rather than a quick win. Toronto’s venture exchange took decades to build the analyst coverage, disclosure norms and specialist investor base that make it work.
Pairing it with startups in the same vehicle is a pragmatic choice, since both categories share the same problem: real prospects, no earnings, and no home on a main board.
What Congress Will Argue About
Suma urgencia forces a legislative timetable but does not guarantee passage. Kast’s coalition does not control both chambers outright, and the opposition’s objection is likely to focus on the Fonavi fund rather than on the down-payment contribution.
The line of attack writes itself: a state bank taking 150,000 mortgages onto its balance sheet is public risk absorbed on behalf of private lenders, and the terms of the repurchase determine who bears the losses if Chilean housing credit deteriorates.
The counter-argument is that BancoEstado already carries substantial mortgage exposure, that the fund is a mechanism rather than a subsidy, and that the alternative is a mortgage market that continues to shrink.
Both arguments turn on the purchase terms, which are in the bill text rather than in the announcement. That is where the debate will actually happen.
More: Chile news in English, every day from The Rio Times.
Frequently Asked Questions
What is MK4?
Chile’s fourth capital markets reform, sent to Congress with maximum urgency on 9 September 2026.
What does it do for homebuyers?
The state contributes three points of a ten percent deposit for first-home buyers who have saved seven points over 30 months.
What is Fonavi?
A new housing fund run by BancoEstado to buy and finance around 150,000 mortgages on 30-year terms.
What is the third element?
A new stock exchange for startups and junior mining companies.
Who is backing it?
Guillermo Tagle of Icare and Banco de Chile chief executive Eduardo Ebensperger, among others in the financial sector.
Sources: Diario Financiero.
This article was drafted with automated assistance and reviewed before publication. How we use AI · Report an error